Banking and Financial Schemes – Complete Banking Awareness Notes 2026 for IBPS, SBI PO and RBI Grade B
Banking and Financial Schemes is one of the highest-frequency topics in banking awareness examinations. This chapter provides complete exam-ready coverage of every government and RBI-sponsored scheme including small savings schemes with current interest rates, financial inclusion schemes (PMJDY, MUDRA, Stand Up India, PM SVANidhi), agricultural credit schemes (KCC, PM-KISAN), pension schemes (APY, NPS), insurance schemes (PMJJBY, PMSBY) and the DBT/JAM infrastructure.
Government and RBI-sponsored financial schemes are among the most consistently tested areas in every banking awareness examination. Questions test scheme names, launch dates, key features, eligibility, interest rates, tenure and implementing ministry. This chapter provides complete, up-to-date coverage of every major scheme with 2025 data.
Small Savings Schemes - Complete Details
Scheme
Rate
Tenure
Max Deposit
Tax (EEE / Others)
Key Feature
PPF (Public Provident Fund)
7.1% p.a.
15 years (extendable in 5-yr blocks)
Rs. 1,50,000/year
EEE — fully exempt
Min Rs. 500/year; loan after 3 years; partial withdrawal from 7th year; protected from court attachment
NSC (National Savings Certificate)
7.7% p.a.
5 years
No limit
80C; interest taxable but deemed reinvested (80C eligible)
No TDS; no premature closure except on death/court order
KVP (Kisan Vikas Patra)
7.5% p.a.
115 months (9 yrs 7 months) — doubles investment
No limit
No 80C; interest fully taxable
Premature closure after 2.5 years; no upper limit; transferable to another person
SSA (Sukanya Samriddhi)
8.2% p.a.
21 years from opening (or marriage after 18)
Rs. 1,50,000/year
EEE — fully exempt
For girl child below 10 years only; max 2 accounts per family; 50% partial withdrawal after age 18 for education
SCSS (Senior Citizen Savings Scheme)
8.2% p.a.
5 years (extendable by 3 years)
Rs. 30,00,000
80C; TDS if interest >Rs. 50,000/year
Age 60+; defence retired from 50; VRS from 55; quarterly payout
MSSC (Mahila Samman Savings Certificate)
7.5% p.a.
2 years
Rs. 2,00,000
No 80C; interest taxable
Only for women and girls; 40% partial withdrawal after 1 year; limited period scheme (till March 2025)
POMIS (Post Office Monthly Income)
7.4% p.a.
5 years
Rs. 9L (single); Rs. 15L (joint)
No 80C; interest taxable; no TDS
Monthly interest payout; principal returned at maturity
Post Office Time Deposit (5-year)
7.5% p.a.
5 years
No limit
80C for 5-year only; interest taxable
Similar to bank FD; government guarantee; available at post offices
Post Office RD
6.7% p.a.
5 years
No limit
No 80C; interest taxable
Min Rs. 100/month; good for disciplined regular savings
Post Office Savings Account
4.0% p.a.
No fixed tenure
No limit
Interest up to Rs. 10,000 exempt; above taxable
Min balance Rs. 500; used for DBT credit
Financial Inclusion Schemes
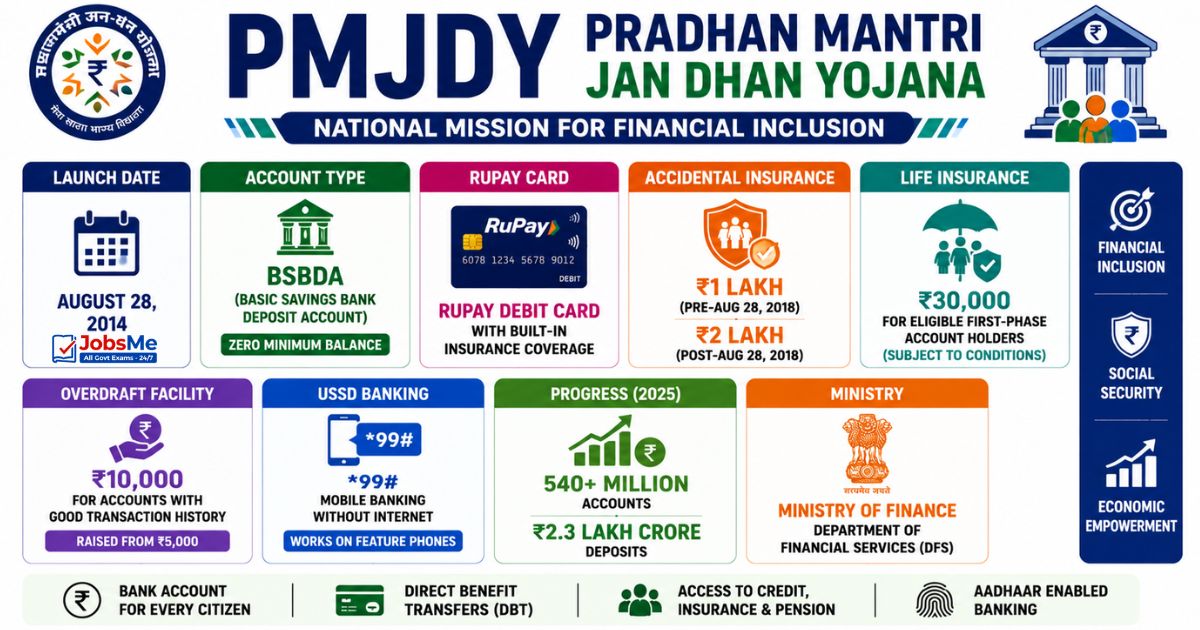
PMJDY - Pradhan Mantri Jan Dhan Yojana
Parameter
Details
Launch Date
August 28, 2014
Account Type
BSBDA (Basic Savings Bank Deposit Account) — zero minimum balance
Rs. 10,00,000 to Rs. 1,00,00,000 (Rs. 10 lakh to Rs. 1 crore)
Enterprise Type
Greenfield enterprises only (new businesses, not expansion of existing)
Bank Branch Target
At least one SC/ST borrower AND one woman borrower per bank branch
Repayment
Up to 7 years with moratorium up to 18 months
Portal
standupmitra.in
Startup India
Parameter
Details
Launch Date
January 16, 2016
DPIIT Recognition
Startups must register at startupindia.gov.in for DPIIT recognition
Tax Exemption
Income tax exemption for 3 out of first 10 years under Section 80-IAC
Patent Fee Rebate
80% rebate on patent filing fees + fast-track examination
Fund of Funds
Rs. 10,000 crore managed by SIDBI to invest in AIFs backing startups
Self-Certification
Compliance with 6 labour and 3 environment laws via self-certification
PM SVANidhi - PM Street Vendor's AtmaNirbhar Nidhi
Parameter
Details
Launch Date
June 1, 2020
Purpose
Working capital loans for street vendors affected by COVID-19
Loan Progression
Rs. 10,000 → Rs. 20,000 → Rs. 50,000 (on timely repayment each time)
Interest Subsidy
7% per annum on timely repayment
Digital Incentive
Up to Rs. 1,200 cashback per year for digital transactions
Ministry
Ministry of Housing and Urban Affairs; SIDBI as nodal agency
Agricultural Credit and Farm Schemes
Kisan Credit Card (KCC)
Parameter
Details
Launched
1998 — based on R.V. Gupta Committee recommendations
Purpose
Flexible revolving credit for crop production, post-harvest expenses, farm asset maintenance, allied activities and personal consumption needs of farmers
Credit Nature
Revolving — farmers draw, repay and redraw within limit through the crop cycle
Validity
5 years with annual review
Credit Limit
Based on scale of finance for crops; increases 10% per year for 5 years
Eligible Borrowers
Owner-cultivators; tenant farmers; oral lessees; share croppers; SHGs and JLGs of farmers; fishermen (extended to allied sectors)
Issuing Banks
Commercial Banks, RRBs, Small Finance Banks, Cooperative Banks
Interest Subvention
Government provides interest subvention; effective rate for prompt repayers kept at 4% p.a. (Kisan Short Term Crop Loan Interest Subvention Scheme)
February 18, 2016 (replaced National Agricultural Insurance Scheme)
Purpose
Crop insurance to protect farmers against crop loss due to natural calamities, pest attack and diseases
Premium by Farmer
Maximum 2% for kharif crops; 1.5% for rabi crops; 5% for horticulture and commercial crops
Premium Balance
Remaining premium shared equally between State and Central Government
Implementing Agency
Agriculture Insurance Company of India (AIC) and empanelled private insurers
Technology
Satellite imagery, drone surveys and smartphone apps for quick crop loss assessment
Pension Schemes
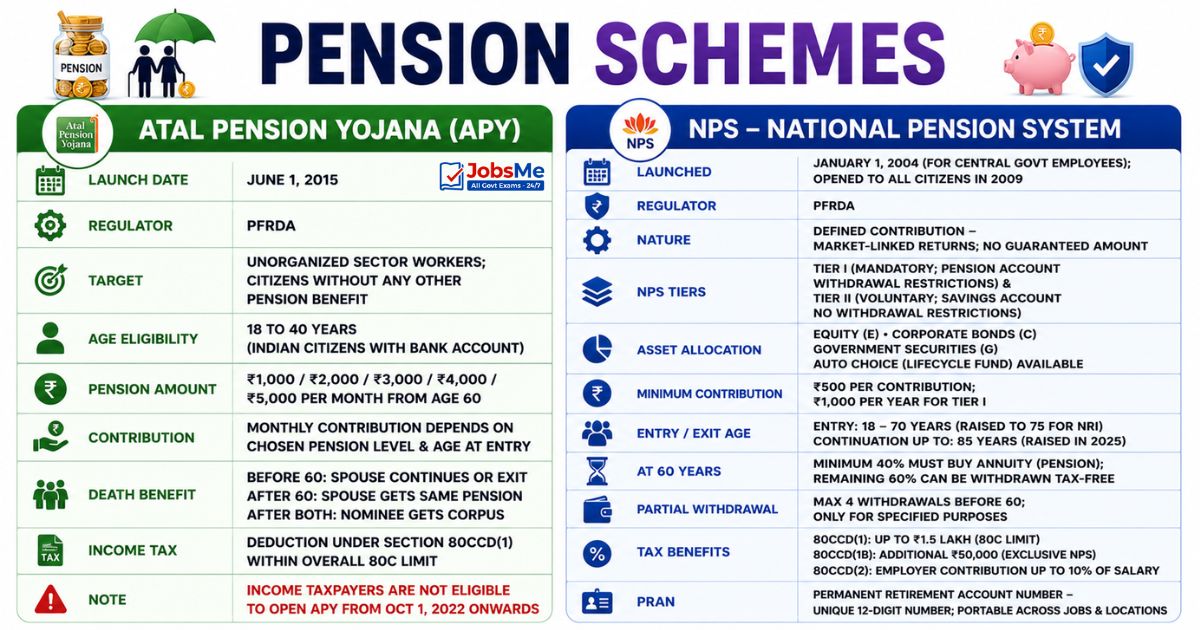
Atal Pension Yojana (APY)
Parameter
Details
Launch Date
June 1, 2015
Regulator
PFRDA (Pension Fund Regulatory and Development Authority)
Target
Unorganized sector workers; citizens without any other pension benefit
Age Eligibility
Indian citizens aged 18 to 40 years with a bank account
Pension Amount
Guaranteed fixed monthly pension of Rs. 1,000 / Rs. 2,000 / Rs. 3,000 / Rs. 4,000 or Rs. 5,000 (subscriber's choice) from age 60
Contribution
Monthly contribution depends on chosen pension level and age at entry — the younger you join, the lower the monthly contribution
Death Benefit
If subscriber dies before 60, spouse can continue contributions or exit; if subscriber dies after 60, spouse receives same pension; after both die, nominee receives accumulated corpus
Income Tax
Contribution qualifies for deduction under Section 80CCD(1) within the overall Section 80C limit
Note
Income taxpayers are not eligible to open APY from October 1, 2022 onwards
NPS - National Pension System
Parameter
Details
Launched
January 1, 2004 for central government employees; opened to all citizens in 2009
Regulator
PFRDA (Pension Fund Regulatory and Development Authority)
Nature
Defined Contribution — market-linked returns; no guaranteed pension amount
NPS Tiers
Tier I (mandatory; pension account with withdrawal restrictions) and Tier II (voluntary; savings account with no withdrawal restrictions)
Asset Allocation
Subscriber chooses allocation among Equity (E), Corporate Bonds (C) and Government Securities (G); Auto Choice (lifecycle fund) is available for those who prefer default allocation
Minimum Contribution
Rs. 500 per contribution; Rs. 1,000 per year for Tier I
Entry/Exit Age
Minimum entry age: 18 years; maximum: 70 years (raised to 75 years for NRI); maximum age for continuation: 85 years (raised in 2025)
At 60 Years
Minimum 40% of accumulated corpus must be used to purchase annuity (pension); remaining 60% can be withdrawn tax-free
Partial Withdrawal
Maximum 4 partial withdrawals before age 60; only for specified purposes (higher education, home purchase, serious illness, disability)
Tax Benefits
Contribution under 80CCD(1) within Rs. 1.5 lakh (80C limit); additional Rs. 50,000 under 80CCD(1B) — exclusive NPS benefit; employer contribution up to 10% of salary under 80CCD(2)
PRAN
Permanent Retirement Account Number — unique 12-digit number allotted to each NPS subscriber; portable across jobs and locations
Government Insurance Schemes
Scheme
Launch
Premium
Cover
Eligibility
PMJJBY (Pradhan Mantri Jeevan Jyoti Bima Yojana)
May 9, 2015
Rs. 436/year (revised; auto-deducted from bank account)
Rs. 2,00,000 life insurance (death due to any cause)
Age 18-50 years with bank/post office account; renewable annually till 55
PMSBY (Pradhan Mantri Suraksha Bima Yojana)
May 9, 2015
Rs. 20/year (auto-deducted)
Rs. 2,00,000 for accidental death or permanent total disability; Rs. 1,00,000 for permanent partial disability
Age 18-70 years with bank/post office account
DBT and JAM Trinity
DBT - Direct Benefit Transfer
Parameter
Details
Launch Date
January 1, 2013 (pilot in 43 districts)
Purpose
Transfer government subsidies and benefits directly into the bank accounts of beneficiaries — eliminating middlemen, reducing leakage and improving targeting
Infrastructure
Built on the JAM (Jan Dhan-Aadhaar-Mobile) trinity
Schemes Covered
Over 1,000 central government schemes including LPG subsidy (PAHAL), MGNREGS wages, PM-KISAN, scholarship schemes, food subsidy, PMJDY overdraft
Savings to Exchequer
DBT has saved the government over Rs. 3 lakh crore by eliminating ghost beneficiaries and duplicate entries since inception
JAM Trinity - The Digital Infrastructure for Financial Inclusion
JAM stands for Jan Dhan + Aadhaar + Mobile. These three components work together to form India's digital financial infrastructure enabling universal, frictionless and leakage-free benefit delivery.
Component
Role
Administered by
Jan Dhan (PMJDY)
Bank account for every citizen — the receiving end of DBT transfers
Ministry of Finance (DFS)
Aadhaar
Unique biometric identity — used for authentication, deduplication and Aadhaar-linked payment routing via AePS
UIDAI (Unique Identification Authority of India)
Mobile
Real-time OTP-based authentication; UPI and USSD-based banking on feature phones; *99# for non-smartphone banking
DoT (Department of Telecommunications) + NPCI
Other Key Schemes
Scheme
Launched
Key Feature
PMAY-G (Pradhan Mantri Awas Yojana - Gramin)
November 20, 2016
Housing for all in rural areas by 2024; Rs. 1.2 lakh (plains) to Rs. 1.3 lakh (hilly/NE) per unit; DBT payment directly to beneficiary
PMAY-U (Urban)
June 25, 2015
Affordable housing for economically weaker sections and low-income groups in urban areas; interest subsidy on home loans under CLSS (Credit Linked Subsidy Scheme)
MGNREGS (Mahatma Gandhi NREGS)
February 2, 2006
Guaranteed 100 days of employment per year to rural households; wages paid directly via DBT to bank/post office accounts
PM Garib Kalyan Anna Yojana (PMGKAY)
April 2020 (COVID relief)
Free ration (5 kg grain per person per month) to NFSA beneficiaries; merged with regular PDS from January 1, 2024
e-RUPI
August 2021
Prepaid digital voucher via QR code or SMS; no bank account needed; targeted welfare delivery; programmable (single-use, specific purpose)
ULI (Unified Lending Interface)
Pilot 2023; expanded 2025
RBI's digital credit delivery platform; consent-based data sharing for frictionless loans to farmers and MSMEs; 3.2 million loans; Rs. 1.75 trillion disbursed (Oct 2025)
UDGAM Portal
August 18, 2023
RBI portal for depositors to search unclaimed deposits across multiple banks; 8.59 lakh users (July 2025)
PRAVAAH
May 28, 2024
RBI's online portal for regulatory approvals (Platform for Regulatory Application, Validation and AutHorisation); single-window for all RBI licence/approval applications
RB-IOS 2021 (Banking Ombudsman)
November 12, 2021
One Nation One Ombudsman; integrated scheme replacing three separate ombudsman schemes; 22 offices; online complaint at cms.rbi.org.in
Memory Tricks - Banking Schemes
Remember MUDRA Categories
Trick: SKT = Shishu (child — up to Rs. 50k), Kishore (teen — Rs. 50k to Rs. 5L), Tarun (adult — Rs. 5L to Rs. 10L). And now Tarun Plus (Rs. 10L to Rs. 20L). Like stages of human growth.
Remember PPF Key Numbers
Trick: PPF = 15 years, 7.1%, Rs. 1.5 lakh max, EEE. Easy to recall: PPF has 3 key numbers — 15 (years), 1.5 (lakh max), 7.1 (rate). EEE = completely tax-free at all three stages.
Remember SSA vs SCSS
Trick: SSA = Girl child, 8.2%, 21 years, EEE. SCSS = Senior citizen (60+), 8.2%, 5 years, max Rs. 30 lakh, quarterly payout. Both earn 8.2% — the highest rates among small savings. SSA = daughter's future; SCSS = parent's retirement.
Remember PMJJBY vs PMSBY
Trick: PMJJBY = Life insurance (Jeevan = life); Rs. 436/year; Rs. 2 lakh cover; age 18-50. PMSBY = Accident insurance (Suraksha = safety/protection); Rs. 20/year; Rs. 2 lakh cover; age 18-70. J for Jeevan (life) — higher premium. S for Suraksha (protection) — lowest premium of any scheme in India.
Remember APY vs NPS
Trick: APY = Atal = Guaranteed pension (fixed Rs. 1k-5k); unorganized sector; 18-40 years. NPS = National = Not guaranteed (market-linked); all citizens; 18-75 years. APY = Assured. NPS = Not guaranteed but potentially higher.
Remember JAM Trinity
Trick: JAM = Jan Dhan (account) + Aadhaar (identity) + Mobile (delivery). JAM unlocks DBT — the three keys that together open the door to direct government benefit delivery.
One-Liners for Quick Revision
PPF: 7.1%; 15 years; max Rs. 1.5 lakh/year; EEE; loan from 3rd year; withdrawal from 7th year.
NSC: 7.7%; 5 years; no TDS; interest reinvested deemed as 80C investment.
KVP: 7.5%; matures in 115 months; money doubles; no upper limit.
SSA (Sukanya): 8.2%; girl child below 10 years; 21 years tenure; EEE; min Rs. 250/year.
SCSS: 8.2%; age 60+; max Rs. 30 lakh; quarterly payout; 80C deduction.
MSSC: 7.5%; women and girls only; max Rs. 2 lakh; 2 years tenure.
Stay updated, revise regularly, and attempt quizzes for better accuracy in UPSC, SSC CGL, IBPS PO/Clerk, SBI, RBI Grade B, RRB NTPC, Defence, and State PSC exams.
Frequently Asked Questions
What is PMJDY and what are its key features?
PMJDY stands for Pradhan Mantri Jan Dhan Yojana, India's national financial inclusion mission launched on August 28, 2014 by PM Narendra Modi. Key features: zero balance savings account; RuPay debit card; accidental insurance of Rs. 2 lakh (for accounts opened after August 28, 2018); overdraft facility of Rs. 10,000; life cover of Rs. 30,000 for eligible beneficiaries. Over 540 million accounts opened as of 2025.
What are the three categories under PM MUDRA Yojana?
PM MUDRA Yojana was launched April 8, 2015. Three categories: Shishu (up to Rs. 50,000 — startups, no collateral), Kishore (Rs. 50,001 to Rs. 5 lakh — businesses with some track record) and Tarun (Rs. 5,00,001 to Rs. 10 lakh — established businesses seeking expansion). A fourth category — Tarun Plus (Rs. 10 lakh to Rs. 20 lakh) — was added in 2024 for businesses that have repaid Tarun loans.
What is the Sukanya Samriddhi Account?
SSA was launched in January 2015 under the Beti Bachao Beti Padhao initiative. It is for girl children below 10 years of age. Interest rate: 8.2% per annum. Annual deposit: minimum Rs. 250, maximum Rs. 1,50,000. Tenure: 21 years from opening or on marriage after 18 years, whichever is earlier. Tax treatment: EEE — investment (80C), interest and maturity are all tax-exempt. Partial withdrawal of 50% is allowed after the girl turns 18 for education.
What is the difference between APY and NPS?
APY (Atal Pension Yojana) provides a guaranteed fixed monthly pension of Rs. 1,000 to Rs. 5,000 and is targeted at unorganized sector workers aged 18 to 40. The pension amount is fixed and guaranteed by the government. NPS (National Pension System) is a market-linked pension scheme available to all citizens (including government employees). NPS returns depend on the performance of the chosen pension fund and asset allocation; there is no guaranteed return. Both are regulated by PFRDA. NPS has a higher potential return but no guarantee; APY has a guaranteed pension amount.